Design the Policy
A properly designed participating whole life policy is structured around your goals, cash flow, protection needs, and long-term financial strategy.
Infinite Banking is a long-term financial strategy that uses properly designed participating whole life insurance to build accessible capital and create greater control over how you finance purchases, investments, business needs, and other opportunities.
It can be a powerful strategy for the right client. But we don't begin with Infinite Banking. We begin with you.
Every financial plan has to answer the same basic questions:
Infinite Banking offers one way to approach those questions.
It uses properly designed participating whole life insurance as part of a broader strategy for accumulating capital, accessing liquidity, managing cash flow, and coordinating long-term financial goals.
The goal isn't simply to own a policy. The goal is to build a financial system that supports what you're trying to accomplish.
I started looking at everyday purchases differently. Every time I paid cash for something, I wasn't just spending money — I was also giving up the opportunity to use that capital somewhere else.
That led me to a bigger question: when I finance something, where does the interest go, and how could I structure my finances so that more of the benefits of my capital stayed within my own financial system?
"The idea was impactful enough that I didn't just recommend it. I implemented it for my own family first, watched how the strategy worked over time, and eventually made it a core part of how I help clients."
Ryan Frey
Founder, Evernorth Financial
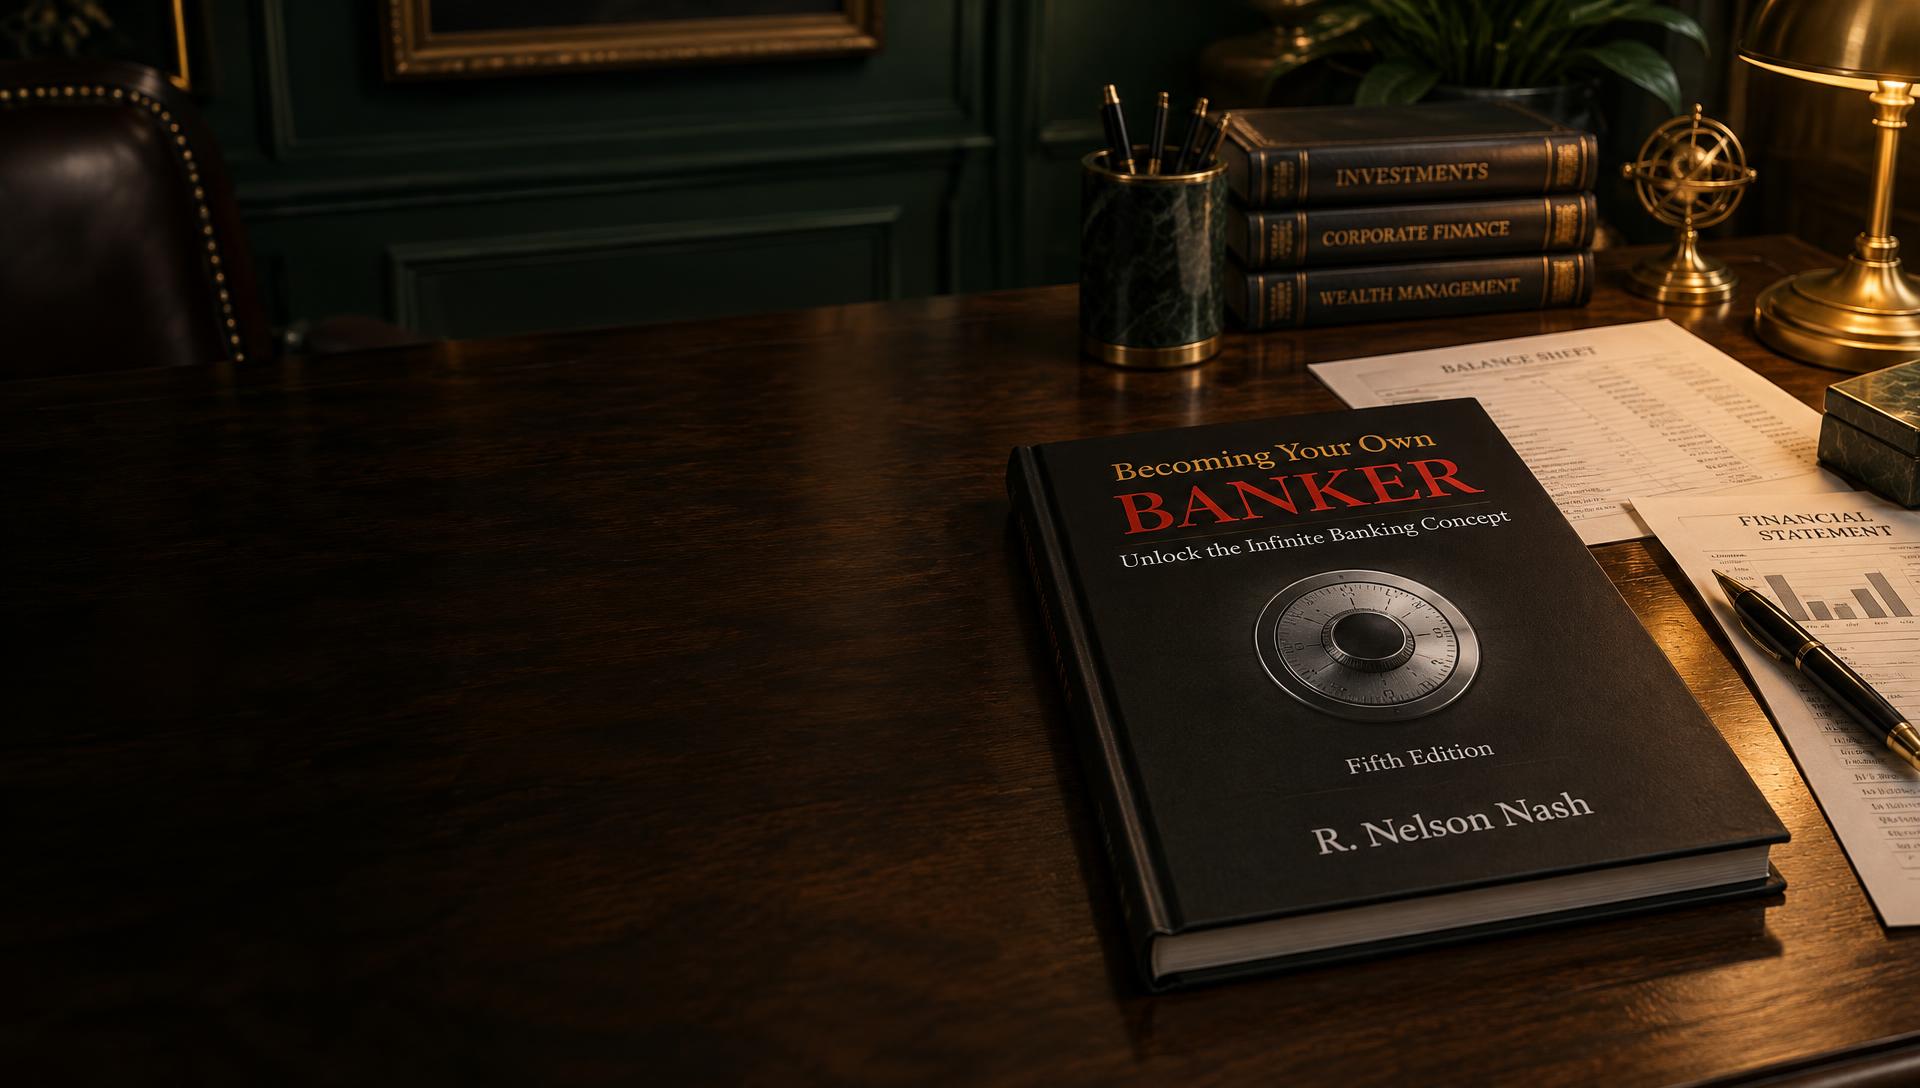
Infinite Banking is a financial strategy popularized by Nelson Nash through his book Becoming Your Own Banker.
At its core, the strategy uses a properly designed participating whole life insurance policy as part of a broader capital and cash-flow strategy.
As cash value builds, the policy can provide access to capital through policy loans for purchases, investments, business needs, or other opportunities, subject to the terms of the policy and lender.
The strategy is about more than the insurance policy itself.
It is about creating a more intentional relationship with your capital — how you accumulate it, access it, use it, and replenish it over time.
It's not about finding a magic financial product. It's about creating a financial system that supports your goals.
A properly designed participating whole life policy is structured around your goals, cash flow, protection needs, and long-term financial strategy.
Premiums build cash value within the policy. The policy includes contractual guaranteed values, with the potential for non-guaranteed dividends depending on the insurer and policy.
You may access capital through policy loans for purchases, investments, business needs, or other opportunities, subject to the policy and lender terms.
As borrowed funds are repaid, capital can become available for future opportunities. The objective is to create a repeatable approach to financing and cash-flow management over the long term.
Policy loans accrue interest and can affect policy values and benefits. The results of a strategy depend on policy design, funding, loan terms, time horizon, and individual circumstances.
Traditional financing and Infinite Banking don't have to be competing systems. The question is whether you want to develop an additional source of capital and liquidity that can complement the rest of your financial strategy.
Important: Policy loans are not free money. They accrue interest and can affect policy values and benefits if not properly managed.
Create an additional source of capital and liquidity that can complement your broader financial system.
Participating whole life insurance includes contractual guaranteed values. Dividends, where applicable, are not guaranteed and may change.
Access capital through policy loans for opportunities, purchases, investments, or business needs, subject to the policy and lender terms.
Cash value can grow within the policy on a tax-advantaged basis, subject to Canadian tax rules and the specific policy structure.
The underlying life insurance provides a death benefit that can form part of your broader family, business, estate, or wealth-transfer strategy.
In appropriate circumstances, a corporation may own life insurance as part of a broader corporate, tax, estate, succession, or capital strategy.
Illustrations are not guarantees. Dividends are not guaranteed and are subject to change. Individual results will vary.
We first look at your goals, your family, your business, your cash flow, your existing financial structure, your protection needs, and your long-term plans.
Then we determine whether Infinite Banking — or another strategy — makes sense.
We also coordinate with your accountant, lawyer, investment professionals, and other specialists where appropriate.
We don't start with Infinite Banking. We determine whether it belongs in your plan.
Ryan Frey · Nearly two decades of industry experience
The right question isn't whether everyone should use Infinite Banking.
It's whether the strategy makes sense for you.
Start with a conversation about your goals, your cash flow, and what you're trying to accomplish. We'll determine whether Infinite Banking belongs in the solution.